The annual SupplySide Global show in Las Vegas, a pivotal event for the health and nutrition industry, once again underscored the paramount importance of education. From Monday afternoon through early Tuesday evening, preceding the official Expo Hall opening on Wednesday, October 28th, a robust series of longer-form educational sessions set the stage for critical industry discussions. These sessions, meticulously curated by the SupplySide content team through extensive brainstorming and invaluable industry input, reflected the most pressing concerns and forward-looking opportunities within the sector. The anticipation surrounding registration numbers for these educational tracks always provides a unique barometer of industry interest, often necessitating last-minute adjustments to accommodate overwhelming demand.
This year, three extended educational topics, excluding specialized Professional Development Workshops, garnered the highest preregistration numbers, signaling key areas of focus for the industry. The top-ranking sessions were:
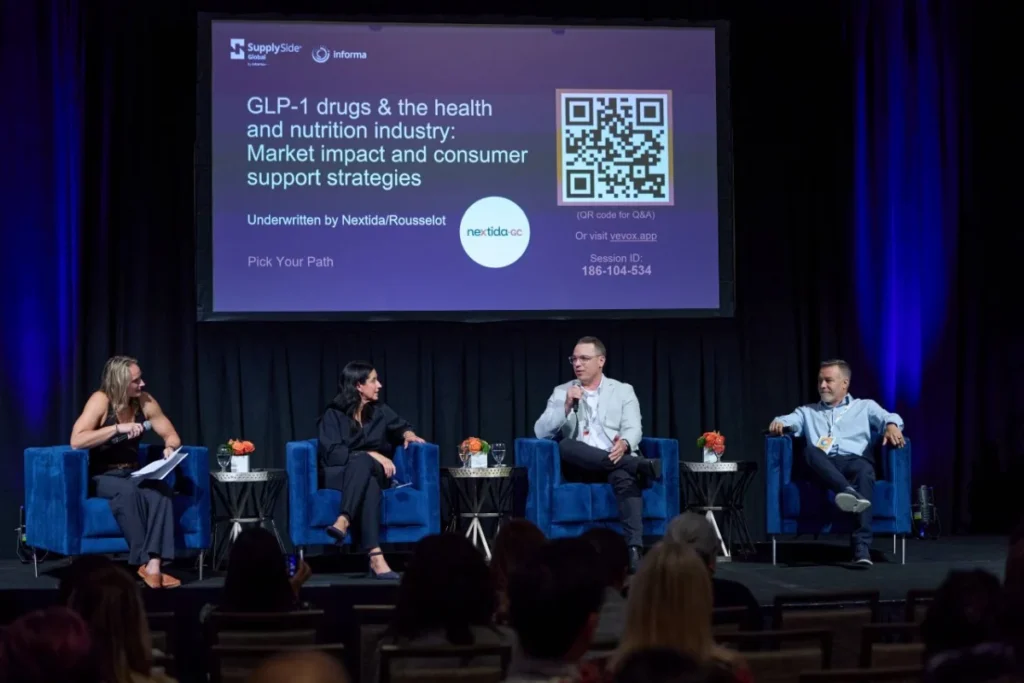
- GLP-1 Drugs & the Health and Nutrition Industry: Market Impact and Consumer Support Strategies
- Supplement Trends 2027: Consumer Insights, Market Predictions, and Innovation Strategies
- Next-Gen Proteins and Collagen: Breakthroughs in Compact Nutrition and Functional Formulation
For registered attendees, these insightful sessions remain accessible for the next six weeks via the show’s mobile application, allowing for continued learning and reference.

The Dominance of GLP-1: Reshaping the Health and Nutrition Landscape
The most heavily attended session, unequivocally, focused on the transformative influence of glucagon-like peptides (GLP-1s) on the health and nutrition industry. This session not only addressed one of the most significant health phenomena of the current era but also introduced an innovative session format that proved highly effective and is slated for future implementation.
The discourse commenced with a comprehensive market analysis presented by Sherry Frey of NielsenIQ (NIQ), providing critical data on the burgeoning GLP-1 market. This was complemented by invaluable perspectives from industry leaders David Despain of Nestlé Health Science and Allyn Kaufmann from Haleon, offering a dual vantage point from major consumer packaged goods (CPG) companies.
Frey’s NIQ data painted a vivid picture of how GLP-1 medications are fundamentally altering consumer behavior and, consequently, the food and beverage industry. Previously, the industry grappled with issues related to emotional eating and daily dietary battles. Now, the landscape has shifted dramatically. The focus has moved from simply satisfying cravings to demanding exceptional nutritional density in smaller portions, coupled with a sophisticated and varied sensory experience, particularly concerning texture. This evolution necessitates a strategic pivot for food manufacturers, emphasizing nutrient-rich, high-impact products.
Allyn Kaufmann highlighted that the current GLP-1 phenomenon is not merely a fleeting trend but a catalyst for generational shifts in how consumers approach food. This includes significant changes in shopping habits, culinary practices, and a pronounced emphasis on the quality of food consumed over sheer quantity. The implications extend to long-term dietary patterns and food system design.
David Despain, speaking from his role as an R&D scientist, echoed these sentiments, underscoring the critical need for products to deliver peak nutrient density per calorie. He emphasized the importance of ensuring adequate protein and fiber intake at every eating occasion, advocating for the strategic distribution of fiber throughout the day to mitigate digestive discomfort. Despain also stressed the imperative for continued scientific research to fully understand the multifaceted effects of GLP-1s and to guide product development responsibly.
Kaufmann reinforced the call for scientific rigor, cautioning the industry against a superficial adoption of ingredients solely for their association with GLP-1s. He urged that any ingredient claiming efficacy in this space must be supported by studies conducted within a GLP-1-user population. "Don’t let the marketing get ahead of the science," Kaufmann advised, imploring the industry to avoid a scattershot approach to GLP-1-related product development.
Sherry Frey offered a crucial insight for broader market appeal: many of the desires of non-GLP-1 users—such as higher protein and fiber content—overlap with those of GLP-1 users. However, she noted that products explicitly marketed towards GLP-1 users might not resonate with the general consumer. Frey suggested that developers should strategically highlight attributes like increased protein and fiber to achieve wider market penetration and appeal.
Following the foundational market data and expert discussions, attendees were presented with a unique "Pick Your Path" breakout session format. These concurrent 45-minute sessions allowed participants to delve into specific consumer segments: those seeking GLP-1 alternatives, individuals transitioning off GLP-1 therapy, and those currently utilizing GLP-1 medications. Each track featured specialized speakers and targeted information. The key learnings from these focused discussions were then shared with the entire audience upon reconvening in the main session room, consolidating the collective knowledge gained.
For professionals operating within or considering entry into the GLP-1 adjacent market, this session provided a wealth of actionable intelligence. It illuminated ongoing opportunities, identified critical areas for improvement, and offered cautionary tales to help avoid common pitfalls. Echoing the broader principles of natural product development, Kaufmann reiterated the necessity of understanding the consumer journey and the underlying problems that individuals are seeking to solve, leveraging scientific innovation to provide effective solutions. The implications of this session are profound, suggesting a significant recalibration of product development strategies to align with evolving consumer health goals and pharmacological interventions.
Navigating the Evolving Supplement Landscape: Data-Driven Insights for 2027
The session dedicated to "Supplement Trends 2027" secured the second-highest preregistration numbers, reflecting the perennial industry interest in understanding the dynamic state of the dietary supplement market. Bill Giebler and Erika Craft from Nutrition Business Journal (NBJ) provided a data-rich overview of market trajectories and consumer behaviors.
Key data points presented included:
- The Rise of the "Health Optimizer": Nearly half (48%) of the general population now identifies as a "health optimizer," indicating a significant shift from a niche segment to a mainstream majority of early adopters of natural products. This demographic is poised to drive future market growth and innovation.
- Demographic Drivers of Health Trends: Younger consumers are increasingly focused on hormonal health optimization, driving demand in categories such as performance-enhancing supplements and emerging trends like protein and creatine. Conversely, older consumers tend to prioritize foundational health, showing a preference for traditional supplements like multivitamins and omega-3 fatty acids.
- Metabolic Health Engagement: Over one-third of surveyed consumers are actively engaged with concepts of metabolic health. However, understanding of this complex area declines with age, with a notable percentage of individuals over 60 expressing uncertainty about its meaning, highlighting a significant educational opportunity.
- Rapid Ingredient Emergence: The speed at which novel ingredients gain traction is accelerating. NAD (nicotinamide adenine dinucleotide) precursors, virtually unknown a few years ago, experienced a remarkable 47% growth in 2025. Other high-growth categories included prebiotics (up 43%), collagen (30%), and digestive enzymes (28%).
- Format Diversification: While non-pill formats, particularly gummies, have been the primary growth engine since 2019, traditional pills, tablets, and capsules continue to maintain steady sales, indicating a persistent consumer preference for these formats among a significant segment of the population.
- E-commerce Dominance on the Horizon: E-commerce is projected to surpass mass-market retail as the largest sales channel for supplements in 2026, underscoring the critical importance of robust online strategies.
The session also featured essential legal and regulatory insights from Zachary Taylor of Epstein Becker Green and Luke Huber of the Council for Responsible Nutrition (CRN). Taylor highlighted that federal authorities face significant capacity constraints in terms of staffing, funding, and bandwidth when overseeing the dietary supplement industry. Huber provided updates on various tariffs and trade concerns impacting the sector.
Rahul Roy presented data from SPINS, reinforcing the growing preventive health mindset among consumers. With 58% of consumers having purchased a dietary supplement in the last year, the data aligns with NBJ’s findings on the increasing emphasis on health and wellness. SPINS’ analysis further indicated that protein and performance nutrition accounted for 45% of total supplement growth in the past year. Roy identified peptide formats, advanced delivery systems (such as liposomal formulations), and next-generation creatine as key areas for future development, noting consumer demand for more targeted benefits, enhanced palatability, and improved product usability.
Aude Ray, representing Nestlé’s premium VMS division (including Solgar and Pure Encapsulation brands), identified longevity and metabolic health as strategic priorities for the company. She also highlighted Solgar’s implementation of an AI-driven initiative at retail to enhance consumer education and product selection. Ray addressed the persistent challenge of "pill fatigue," acknowledging that while pills and capsules often offer optimal active ingredient delivery, the industry must continue to innovate and provide nutrients in diverse formats to meet consumer preferences.
In the concluding panel, data experts offered distinct yet complementary perspectives. Roy commended the industry’s progress in formulating women’s health products with appropriate dosages. Craft provided a concise definition of metabolic health—the body’s process of energy conversion—and pointed to ongoing growth in this category due to its widespread impact and multifaceted approach. Giebler advised stakeholders to closely monitor ingredient trends, predicting that innovations emerging in the dietary supplement space are likely to permeate the food industry through bars, beverages, and other novel product formats. The implications here are clear: an integrated approach to health and wellness across food and supplement categories is becoming increasingly vital.
The Protein Revolution: Addressing Demand, Quality, and Innovation
The third most popular educational session, focusing on "Next-Gen Proteins and Collagen," delved into the surging consumer demand for protein, exploring novel sourcing, optimization strategies for traditional sources, and the critical interplay between taste, texture, and nutritional value.
Brad Meyers of alt-protein company The Fynder Group characterized consumer demand for protein as "insatiable." This sentiment was echoed by audience polling, which revealed rising whey protein costs as a significant concern for many. The session explored innovative protein sources and strategies to maximize the utility of existing protein resources.
A recurring theme throughout SupplySide Global was the mandate for products delivering superior taste and texture, often termed "T-squared." However, in the protein category, speakers noted a unique consumer dynamic: a degree of tolerance for less-than-ideal sensory attributes if the product effectively helps individuals meet their protein intake goals.
Sam Kressler of Stir Innovation cautioned against complacency, stating, "It can’t be sandy when it’s supposed to be smooth." While acknowledging that consumers might initially overlook minor sensory compromises for protein intake, he stressed that this tolerance wanes quickly once superior-tasting alternatives become available. Meyers concurred, emphasizing that while marketing may secure an initial purchase, sustained brand loyalty hinges on exceptional taste.
Protein quality emerged as a significant discussion point. Meyers observed that many consumers lack a deep understanding of or actively seek out PDCAAS (protein digestibility-corrected amino acid score), a standard measure of protein quality. Nelson Bahri from the American Egg Board expressed optimism regarding future consumer education on protein sources, drawing parallels to the industry’s success in educating consumers about "good" and "bad" carbohydrates and oils. He highlighted protein’s unique position as a nutrient that has not faced widespread negative messaging, suggesting that understanding basic protein quality markers is an achievable educational goal for consumers.
The intersection of GLP-1s and protein was also explored. Kressler noted that while consumers may not fully grasp the need for slower-digesting proteins, they recognize the importance of fiber. Bahri voiced concerns about the potential for an overemphasis on GLP-1-driven dietary modifications, suggesting that combining GLP-1 medications that slow digestion with foods that also slow digestion might not always yield optimal health outcomes.
Kressler highlighted the paradox that "everyone just wants protein—GLP-1 user or not," yet many individuals already consume more protein than their bodies require. Drawing from the GLP-1 session’s themes, Meyers advised product developers to emphasize nutritional value rather than direct GLP-1 messaging, as consumers generally resist being marketed to as "dieting."
Bahri posited that the food industry has historically been driven by value and serving size, with "big and cheap" often being the prevailing consumer preference in America. He suggested that GLP-1s have fundamentally altered this dynamic, leading to a demand for nutrient-dense, exceptionally tasty, and texturally appealing "two-bite" foods. Despite these evolving challenges, Bahri urged formulators to remain proactive and avoid complacency, emphasizing the continuous need for innovation and improvement.
Kyle Failla of Perfect Day, a company scaling precision fermentation manufacturing, offered encouraging remarks, stating, "At the end of the day, all proteins have a place in the formulator’s tool belt. That’s something we can be really proud of as an industry overall." This sentiment underscores the industry’s collective progress and the diverse opportunities available in the protein sector. The implications of this session point towards a future where protein product development must balance novel sourcing with enhanced sensory appeal and clear communication of quality and nutritional benefits, all while navigating the influence of emerging pharmaceutical trends.