The global dietary supplement industry is experiencing a seismic shift, characterized by substantial financial maneuvers and a recalibrating investor appetite. Two landmark transactions – Procter & Gamble’s $3.8 billion acquisition of Thorne and Nestlé’s $1 billion divestiture of its wellness platform to Yellow Wood Partners – signal a pivotal moment for the sector. These deals underscore the immense value and evolving landscape of a market that, according to the Nutrition Business Journal, was projected to reach $74.15 billion in the U.S. by 2025. While consumer demand for wellness products continues to surge, driven by a growing investment in personal health, a dynamic interplay of corporate strategies and market forces is reshaping the industry’s future for both established brands and the critical ingredient manufacturers that underpin them.
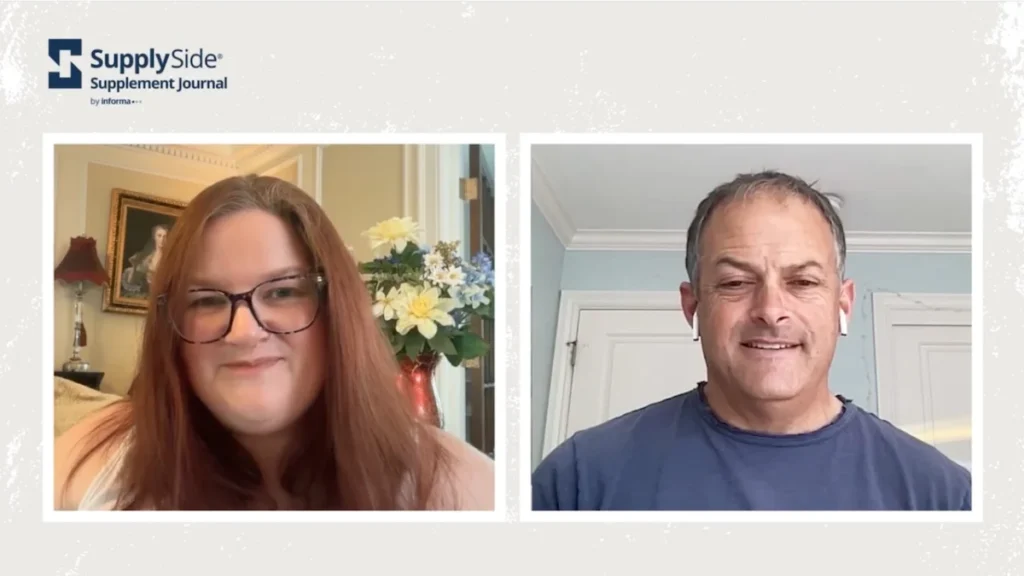
Mike Dovbish, executive director of Nutrition Capital Network, a prominent advisory firm specializing in the nutrition industry, offers a keen perspective on these developments. He notes that the current business environment is exceptionally conducive to significant financial activity. "There’s definitely less red tape, and it’s a pro-business environment," Dovbish stated, highlighting a regulatory and economic climate that encourages mergers, acquisitions, and strategic investments. This favorable backdrop is not solely responsible for the recent flurry of deals; the very nature of the supplement business is undergoing a transformation. Many successful supplement companies, often initiated by visionary founders, are reaching a stage where liquidity events become attractive. As these founders transition, they frequently reinvest their capital back into the industry, either as strategic investors or active operators, thereby injecting fresh capital and fostering further innovation and consolidation.
A Landscape of Strategic Divestitures and Acquisitions
The recent financial activity paints a compelling picture of strategic recalibration among major consumer goods conglomerates. Procter & Gamble’s (P&G) substantial investment in Thorne, a move finalized in early 2024, represents a significant bet on the burgeoning personalized nutrition and health optimization market. Thorne, known for its science-backed approach and high-quality supplements, aligns with P&G’s broader strategy to expand its reach into consumer health and wellness categories. This acquisition positions P&G to leverage Thorne’s established brand equity and direct-to-consumer channels while potentially integrating its innovations into P&G’s extensive distribution networks. The $3.8 billion valuation reflects the premium placed on companies with strong scientific credentials and a loyal customer base in the health and wellness space.
Conversely, Nestlé’s decision to divest its entire health science nutrition business, including its supplement brands, for approximately $1 billion to private equity firm Yellow Wood Partners, signals a different strategic direction. This move, also occurring in early 2024, suggests Nestlé’s intent to streamline its portfolio and focus on core areas where it sees greater growth potential or operational synergies. Yellow Wood Partners, with a history of acquiring and growing consumer brands, is expected to revitalize these supplement assets, potentially through operational improvements and targeted market strategies. The divestiture allows Nestlé to unlock capital while enabling the acquired brands to benefit from a more focused ownership structure.
These contrasting yet significant transactions, occurring in close temporal proximity, highlight a period of dynamic portfolio management within the consumer packaged goods sector, with a clear emphasis on the lucrative and growing health and wellness market.
The Supplement Market: A Deep Dive into Growth and Consumer Behavior
The robust financial activity within the supplement sector is intrinsically linked to sustained consumer interest in health and well-being. Data from the Nutrition Business Journal indicates a market trajectory that has consistently outperformed many other consumer goods categories. The projected $74.15 billion valuation for the U.S. market in 2025 is not an anomaly but a reflection of deep-seated consumer trends. Consumers are increasingly viewing supplements not as discretionary purchases but as essential investments in preventative health, longevity, and enhanced quality of life.
This elevated consumer demand is fueled by several factors:
- Increased Health Consciousness: A growing awareness of the link between diet, lifestyle, and long-term health outcomes drives consumers to seek out nutritional support.
- Aging Demographics: As populations age globally, there is a heightened focus on maintaining vitality, cognitive function, and physical health, creating a strong demand for age-specific supplements.
- Personalized Nutrition: Advances in understanding individual genetic predispositions, microbiome composition, and lifestyle needs are paving the way for more tailored supplement regimens. Brands that can offer personalized solutions or scientifically validated ingredients for specific health goals are particularly attractive.
- Digital Health and Wellness: The proliferation of health tracking devices, online wellness platforms, and accessible health information empowers consumers to take a more proactive role in managing their health, often leading them to explore supplement options.
- Post-Pandemic Health Focus: The COVID-19 pandemic significantly amplified public interest in immune health and overall well-being, creating a sustained demand for supplements aimed at bolstering the body’s defenses and promoting general health.
The market’s growth is also characterized by a diversification of product offerings. Beyond traditional vitamins and minerals, the industry is witnessing significant expansion in categories such as probiotics, omega-3 fatty acids, plant-based proteins, adaptogens, and nootropics, catering to a wider array of consumer needs and preferences. This expanding product landscape creates fertile ground for innovation and investment, attracting both established players and new entrants.
A Pro-Business Environment and its Catalytic Effect
Mike Dovbish’s assertion of a "pro-business environment" is supported by observable trends in capital availability and regulatory receptiveness. For years, the dietary supplement industry has navigated a complex regulatory framework, primarily overseen by the U.S. Food and Drug Administration (FDA). While regulatory scrutiny remains, there appears to be a more streamlined approach to business operations and investment compared to periods of heightened uncertainty. This stability, coupled with a growing understanding and acceptance of the supplement sector’s economic significance, fosters confidence among investors and acquirers.
The concept of "liquidity" for founder-led companies is a critical element in this new era. Many of the prominent supplement brands today were built from the ground up by entrepreneurs with a deep passion for health and nutrition. As these companies mature, founders often reach a point where they seek to realize the financial rewards of their efforts. This can involve selling their stake, either partially or entirely, to larger corporations or private equity firms. The capital generated from these transactions is not necessarily withdrawn from the industry. Instead, it often flows back into new ventures, strategic investments in emerging companies, or support for research and development, creating a virtuous cycle of growth and innovation.
This phenomenon is particularly evident in the functional food and nutraceutical space, where Dovbish has extensive experience. He observes that the ability for founders to achieve a successful exit and then re-enter the market as investors or advisors injects not only capital but also invaluable expertise and strategic vision. This dynamic is crucial for nurturing the next generation of supplement brands and for driving the industry forward.
Unlocking Opportunities for Ingredient Manufacturers
While the recent high-profile transactions have primarily involved finished supplement brands, Dovbish points to a significant and largely untapped opportunity for ingredient companies. These are the businesses that develop, manufacture, and supply the raw materials – the vitamins, minerals, botanical extracts, probiotics, and other bioactive compounds – that form the basis of dietary supplements.
"There actually aren’t enough ingredient companies, particularly those that are backed with science, that are of scale to meet the demand," Dovbish articulated. This statement highlights a critical bottleneck in the supply chain. As consumer demand for scientifically validated, high-quality supplements continues to grow, the pressure on ingredient suppliers intensifies. Companies that can demonstrate rigorous scientific backing for their ingredients, ensure consistent quality and purity, and scale production to meet burgeoning demand are exceptionally well-positioned for success.
The implications for ingredient manufacturers are profound:
- Increased Demand: The expanding supplement market naturally translates to higher demand for its core components.
- Premium on Science and Innovation: Brands are increasingly scrutinizing the scientific evidence behind the ingredients they use. Companies with robust clinical data, proprietary formulations, and patented technologies will command premium pricing and secure longer-term contracts.
- Consolidation Potential: The current landscape suggests that ingredient companies that can achieve significant scale and possess strong scientific credentials may become attractive acquisition targets themselves, or conversely, may be well-positioned to acquire smaller, innovative players.
- Investment Opportunities: Dovbish’s hope that investor demand will spur capital raises and innovation among ingredient companies is a critical forward-looking statement. Investors are recognizing that the underlying science and manufacturing capabilities of the ingredient sector are fundamental to the success of the entire supplement industry.
The trend towards personalized nutrition and functional ingredients targeting specific health outcomes (e.g., gut health, cognitive function, immune support, stress management) further elevates the importance of specialized ingredient suppliers. Companies that can provide novel or highly efficacious ingredients in these areas are poised for substantial growth.
The Cyclical Nature of Mergers and Acquisitions in the Supplement Sector
Dovbish’s analysis extends to a prediction of continued mergers and acquisitions (M&A) activity, albeit with a notable shift in focus. He anticipates a period where transactions involving finished supplement brands might experience a temporary slowdown, while activity surrounding ingredient companies escalates.
"I could really see (ingredient companies) take the lead in terms of M&A while supplements take a little bit of a pause while companies grow to fill the next wave of M&A," Dovbish explained. This foresight suggests a strategic rebalancing within the industry. As major conglomerates and private equity firms have made significant inroads into the branded supplement space, their attention is now turning to the foundational elements of the industry. Ingredient suppliers, especially those with strong scientific portfolios and scalable operations, represent the next frontier for strategic investment and consolidation.
This cyclical pattern is not uncommon in evolving industries. Initial consolidation often targets established brands that offer immediate market share and brand recognition. As these segments become more saturated or mature, investors and acquirers look to the upstream components of the value chain – in this case, the ingredient suppliers – to secure supply, drive innovation, and capture further value.
The potential for ingredient companies to become the primary drivers of M&A activity in the coming years could lead to:
- Strategic Partnerships: Increased collaboration and partnerships between ingredient suppliers and supplement brands to co-develop new products and ensure supply chain security.
- Vertical Integration: Larger companies may seek to acquire ingredient suppliers to gain greater control over their supply chains, product quality, and innovation pipelines.
- Focus on R&D: A heightened emphasis on research and development within ingredient companies, driven by the demand for novel, science-backed solutions.
- Talent Acquisition: The acquisition of specialized scientific and technical talent within ingredient companies will become increasingly valuable.
Dovbish concludes with an optimistic outlook, stating, "It could be a really interesting time." This sentiment captures the dynamic and transformative period the supplement industry is currently navigating. The confluence of strong consumer demand, favorable economic conditions, and strategic corporate repositioning is creating a fertile environment for growth, innovation, and significant financial activity, particularly for the science-driven ingredient manufacturers that form the backbone of this vital sector. The coming years promise to be a period of significant evolution, offering both challenges and unprecedented opportunities for stakeholders across the entire supplement value chain.
About the Author:
Devon Gholam, Ph.D., is an editor at SupplySide Supplement Journal. Her nearly two decades in the functional food and nutraceutical industry span product development, innovation, technical sales, and technical writing at companies including Kellogg Co., Ganeden Biotech (now part of Kerry), and Step Change Innovations. Dr. Gholam is passionate about women’s health and the impact of GLP-1 medication on the food, beverage, and supplement industries. She is eager to share her trademark passion for knowledge and credible science to foster an innovative and collaborative spirit within the nutraceutical community.