The global medical technology landscape is currently grappling with a complex convergence of economic volatility, rapid clinical shifts, and an escalating threat environment. At the recent MedTech Conference hosted by AdvaMed in Boston, the industry’s most influential executives gathered to delineate the strategies required to navigate these challenges. From the Chief Executive Officers of Medtronic and Boston Scientific to the leadership of Stryker and Mass General Brigham, the consensus was clear: the path forward requires a ruthless focus on operational simplicity, clinical safety in decentralized settings, and a robust defense against digital incursions.
As the healthcare sector continues to recover from the structural disruptions of the early 2020s, the conference served as a barometer for the industry’s health. While innovation remains the primary driver of value, the "how" of medtech—how devices are used, how they are protected, and how they are paid for—has become as critical as the "what."
The Doctrine of Simplicity: Medtronic’s Approach to Clinical Workflow
In an era of advanced robotics and artificial intelligence, Medtronic CEO Geoff Martha offered a sobering reminder that technological sophistication means little if it complicates the lives of overburdened healthcare workers. During a keynote discussion, Martha emphasized that for any new technology to achieve meaningful scale, it must integrate seamlessly into existing clinical workflows.
"What’s the difference between a toy and something that’s scaled? Obviously, the economics matter a lot. But it has to be simple," Martha stated. He highlighted a recurring pitfall in device development: the tendency to overlook the temporal and cognitive costs of new procedures. Martha noted that even a seemingly minor five-minute addition to a standard hour-long surgical case can be a dealbreaker in a modern hospital environment.
This focus on simplicity is a direct response to the global shortage of healthcare labor. According to data from the World Health Organization, there is a projected shortfall of 10 million health workers by 2030. In this context, medical device firms are no longer just selling tools; they are selling efficiency. Martha’s "simple wins" philosophy suggests that Medtronic and its peers are increasingly prioritizing the reduction of "procedural friction" as a core competitive advantage.
The Migration to Outpatient Care: Boston Scientific and the ASC Evolution
One of the most significant structural shifts in healthcare delivery is the migration of complex procedures from traditional hospital settings to Ambulatory Surgery Centers (ASCs). This trend, driven by the dual pressures of cost containment and patient preference, was a focal point for Boston Scientific CEO Mike Mahoney.
Historically, ASCs were the domain of lower-complexity procedures. However, the success of orthopedic surgeries—specifically total hip and knee replacements—in these settings has paved the way for more specialized fields. Mahoney pointed to cardiology as the next frontier for this transition.
"The ASC is a tremendous patient benefit," Mahoney noted, explaining that moving procedures out of hospitals allows those institutions to focus on the most acute, high-risk cases. He specifically highlighted the recent approval of Pulsed Field Ablation (PFA) procedures for outpatient settings as a landmark development. PFA, a non-thermal method for treating atrial fibrillation, represents a high-demand procedure that can now be diverted to more cost-effective facilities.
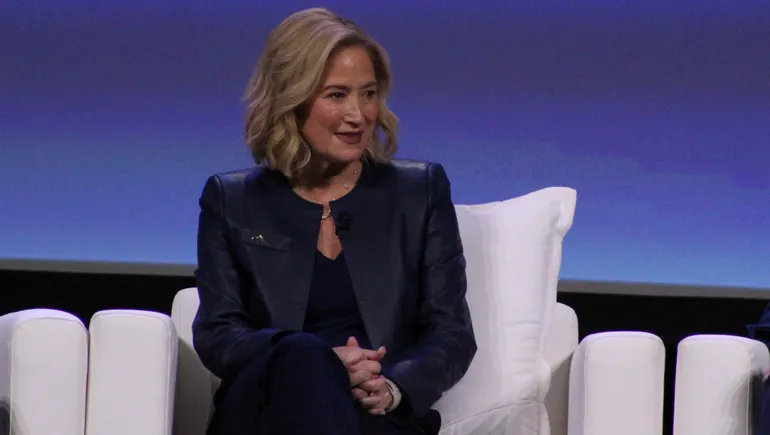
However, the transition to ASCs is not without hurdles. Mahoney emphasized that the threshold for safety and quality must be exceptionally high because these facilities lack the comprehensive emergency infrastructure of a full-scale hospital. "The safety profile has to be incredibly high," he cautioned, noting that "referral safety"—the confidence that a patient can be safely managed outside a hospital—is the primary metric for cardiologist adoption in the outpatient space.
Resilience Under Fire: Stryker’s Cybersecurity Crisis Management
While clinical innovation continues, the back-office infrastructure of the medtech industry faces an existential threat from cybercrime. Spencer Stiles, Stryker’s Chief Operating Officer and incoming CEO, provided a rare, candid look into the company’s experience with a major cyberattack earlier this year.
Recalling the morning of March 11, Stiles described the immediate paralysis that occurs when a global corporation’s digital nervous system is compromised. "Just imagine taking those phones and wiping them clean, and then trying to get through the rest of your day," Stiles said, illustrating the magnitude of the disruption.
The Stryker experience reflects a broader trend: healthcare is now the most targeted sector for ransomware and data breaches. According to the 2024 IBM Cost of a Data Breach Report, the average cost of a healthcare breach has reached nearly $11 million, the highest of any industry.
Stiles’ strategy for navigating such turbulence centers on three pillars: prioritization, safety, and transparency. By focusing on the safety of patients and employees first, and then maintaining open lines of communication with customers, the company was able to manage the crisis. His testimony serves as a blueprint for an industry that is increasingly reliant on connected devices and cloud-based data management, making cybersecurity a fundamental component of patient safety.
The Economic Burden of Modern Medicine: A Provider Perspective
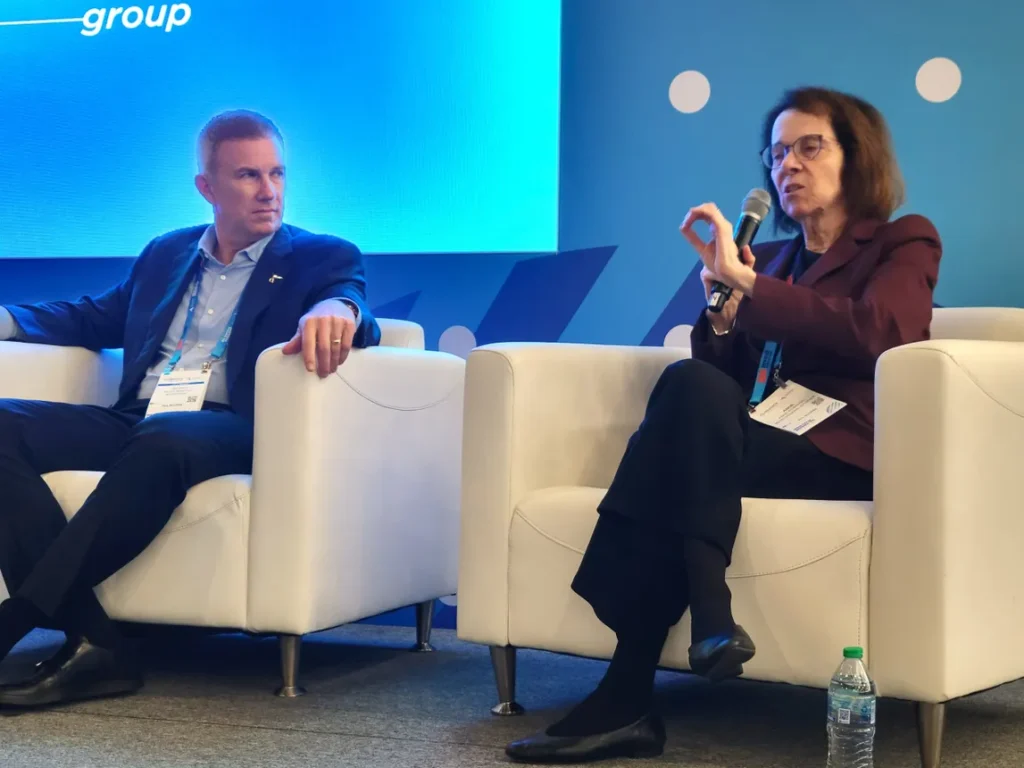
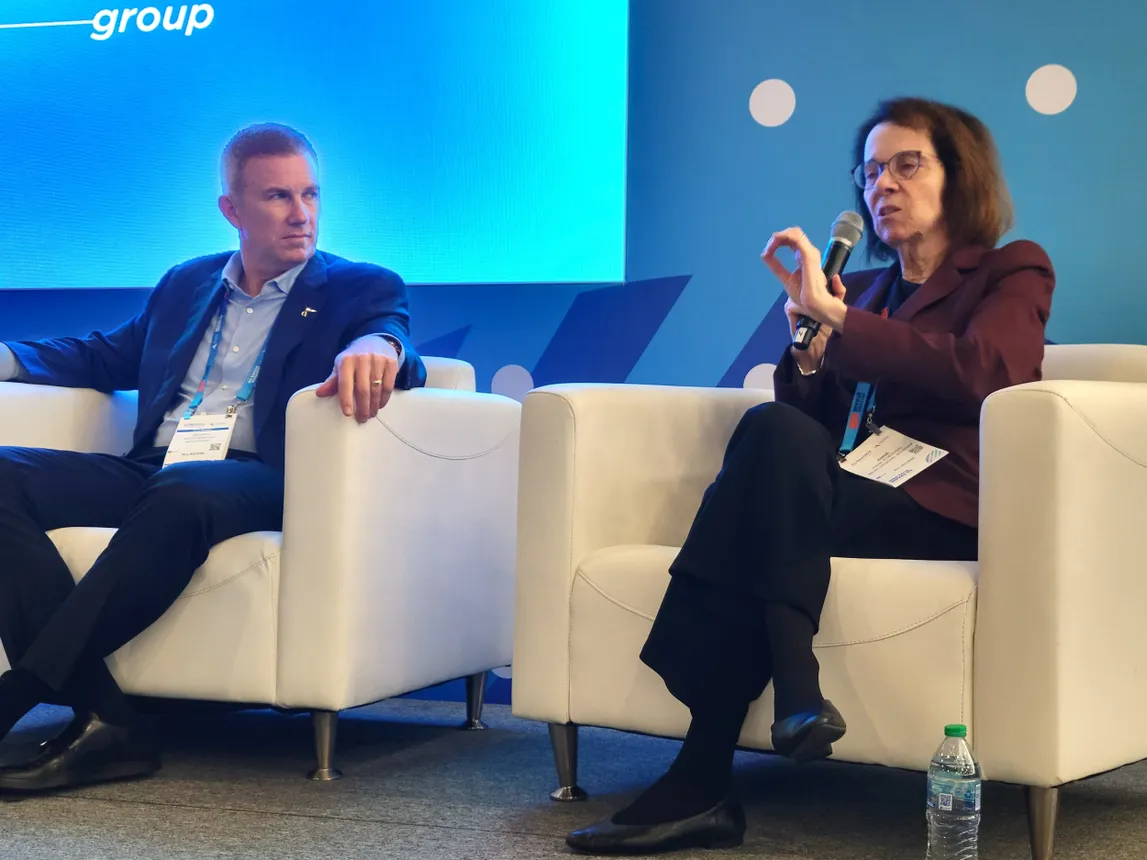
The dialogue at AdvaMed was not limited to manufacturers. Dr. Anne Klibanski, CEO of Mass General Brigham (MGB), provided a stark assessment of the financial pressures facing large-scale health systems. Her insights highlighted the tension between the rising cost of medical innovation and the shrinking margins of providers.
Dr. Klibanski revealed that MGB monitors approximately 200,000 medical devices across its system. In terms of implants alone, the system spends over $420 million annually—a figure she expects to surpass the $500 million mark in the near future. The majority of these costs are concentrated in cardiothoracic procedures.
"The constant increase in cost, whether it’s labor, supply chain, pharmaceutical—I could go on and on. All of the economic factors that hit everybody in every business really affect us profoundly," Klibanski said.
She also raised concerns about the "Medicaid redetermination" process, where millions of Americans are losing coverage as pandemic-era protections expire. This shift increases the burden of uncompensated care on hospitals, further tightening the budgets available for purchasing new medical technologies. For medtech firms, the message is clear: hospitals are looking for partners who can help them manage total costs, not just sell them the latest device.
Leading Through Market Skepticism: The Insulet Philosophy
Insulet CEO Ashley McEvoy addressed the challenge of leading a medtech firm through periods of intense market volatility and investor skepticism. With stock markets reacting sharply to the rise of GLP-1 weight-loss drugs and their potential impact on chronic disease management, leaders in the diabetes and cardiovascular space have had to defend their long-term value propositions.
McEvoy argued that leadership in "tough markets" requires a laser focus on the mission and a commitment to an "open ecosystem" of innovation. She emphasized the importance of maintaining an entrepreneurial spirit even as a company scales.
"Leadership is about being in service of others, creating the right conditions where people can learn and contribute," McEvoy said. Her comments reflect a broader sentiment among medtech executives that the industry must look beyond quarterly earnings and stay focused on long-term clinical outcomes to regain "believers" in the investment community.
Chronology of Challenges: A Year of MedTech Transformation
The discussions at the 2024 conference reflect a timeline of events that have reshaped the industry over the past twelve months:
- Q1 2024: The Cybersecurity Wave. The attack on Stryker in March followed high-profile breaches at other healthcare entities, forcing a re-evaluation of digital supply chain security.
- Q2 2024: The GLP-1 Discourse. The rapid adoption of obesity medications led to market fluctuations for medtech firms specializing in diabetes and cardiovascular health, requiring leaders like McEvoy to articulate the complementary nature of these therapies.
- Q3 2024: The ASC Regulatory Shift. New CMS reimbursement policies further incentivized the migration of complex procedures to outpatient centers, accelerating the strategies discussed by Boston Scientific’s Mahoney.
- Q4 2024: The Economic Reality Check. As reflected in Dr. Klibanski’s remarks, the cumulative impact of inflation and labor costs has forced a shift in hospital procurement strategies, moving from a "best-in-class" acquisition model to a "best-value" model.
Broader Impact and Future Implications
The insights shared at AdvaMed 2024 suggest that the medtech industry is entering a "mature innovation" phase. The era of developing technology for technology’s sake is giving way to an era of "pragmatic innovation."
For manufacturers, this means that the clinical efficacy of a device is no longer the sole metric of success. A device must also be "workflow-neutral" or "workflow-positive," it must be cyber-resilient, and it must offer a clear economic pathway for use in lower-cost settings like ASCs.
Furthermore, the relationship between medtech firms and health systems is evolving into a more integrated partnership. As Dr. Klibanski noted, the sheer volume and cost of implants require a collaborative approach to inventory management and outcomes tracking. Companies that can provide data-driven insights into how their devices reduce the total cost of care—not just the cost of a single procedure—will be the ones that thrive in this constrained economic environment.
As the conference concluded, the overarching theme was one of resilient adaptation. Whether navigating a total system wipeout from a cyberattack or the slow-moving shift of cardiology into the outpatient space, the leaders of the medtech industry are prioritizing the human element: the surgeon’s time, the administrator’s budget, and, ultimately, the patient’s safety. The success of the next generation of medical technology will be measured not by its complexity, but by its ability to simplify the increasingly complex world of modern medicine.